

Experian®

- 205.94K Reviews
- 4.7
- Downloads
- 10,000,000+
Our take on Experian® from Appgk
I approached Experian® as a practical finance app rather than something to open only when applying for a loan. That distinction matters. Its main value is helping me keep credit information and everyday financial awareness in one place, so I can check my position, notice changes, and make better decisions before a money problem becomes urgent. It is free, aimed at everyone, and developed by Experian, a name closely associated with credit information.
The app has a strong reputation on mobile, with a 4.7 average from around 717 thousand ratings and more than 10 million installs. Those figures suggest that it has become a familiar tool for people who want a simpler way to stay connected with their credit. My experience is that it works best when treated as part of a repeatable financial routine, not as a magic button for improving every part of someone’s money life.
How I use Experian® as a credit-checking routine
My baseline workflow is deliberately simple. I open the app, review the main credit information presented to me, look for anything unfamiliar, and then leave with one clear action if something needs attention. That action might be checking a bill, reviewing a recent account change, or deciding to delay a new application until I understand how it could affect my wider financial plans.
This routine is more useful than repeatedly refreshing the app without a purpose. Credit information can feel abstract when it is viewed as a single score, but the practical questions are usually more specific: does the information look familiar, has anything changed, and is there a reason to investigate? Experian® is strongest when it helps turn those questions into a quick habit.
Best Parts of Experian®
Things to Keep in Mind About Experian®
I would not use a credit app as my only source of truth for personal finances. It does not replace a bank account app, a proper budget, or the documents connected with a loan or card. Instead, I see it as a monitoring layer between those services and major financial decisions. The bank app shows transactions; a budgeting tool shows spending patterns; this app gives me a separate view of credit-related information.
A realistic everyday example is preparing to move house. Before contacting lenders or making a major application, I can use the app to review my current position and check whether the information looks consistent with my own records. If something seems wrong, discovering it early gives me time to investigate rather than finding it during a stressful application process. That is a modest workflow, but it is much more valuable than opening the app only after a rejection.
News and Features Related to Experian®

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
The same habit helps when I am not planning to borrow. Someone might notice an unfamiliar item, an unexpected change, or information that no longer reflects their circumstances. The app cannot solve every issue instantly, but it can prompt the right next step. In my view, that awareness is the most important benefit for ordinary users.
What I check before trusting the overview
I try to separate what the app displays from what I personally know. A polished summary can make financial information feel definitive, but I still compare it with statements, account details, and correspondence when something matters. This is particularly important before making a major application, because an overview is useful for orientation while official documentation remains important for decisions.
Don't want to read the full review?
I also avoid treating a score as a personal grade. A change can be worth understanding without being a reason to panic. My first response is to look for context and timing, then decide whether the change is expected. That mindset prevents the common mistake of checking repeatedly and reacting emotionally to every movement.
For someone new to credit monitoring, the app is approachable because it places a complicated subject inside a familiar phone interface. However, beginners should still learn the difference between monitoring information and actively changing their financial position. Checking the app is passive; paying obligations on time, reducing expensive borrowing, and correcting errors require action elsewhere.
Screenshots
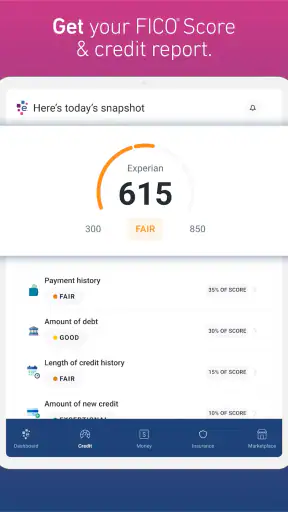
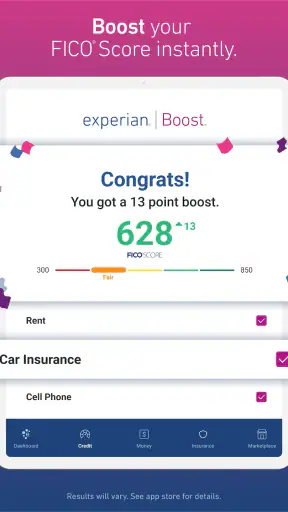
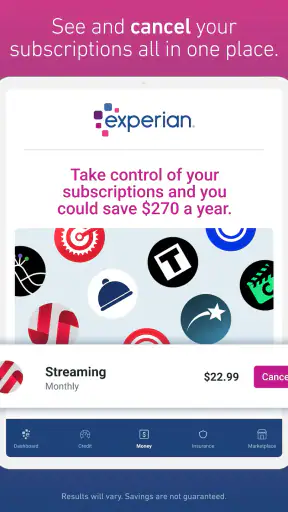
Settings and privacy choices I would review first
When I install a finance app, I do not rush through the setup. I read the available choices carefully and decide which alerts are genuinely useful. A notification that prompts me to review an important change can support a good habit, while too many routine alerts can make me ignore the one that matters. The right balance depends on how often I already check my finances.
I also review notification visibility on the phone itself. Financial messages appearing openly on a lock screen may be inconvenient in a shared environment. This is not a criticism unique to Experian®; it is a sensible precaution for any app connected with personal money information. I prefer alerts that remind me to open the app without revealing unnecessary detail in public.
Access security deserves the same attention. I use the strongest sign-in method available to me and avoid leaving a finance session open when I am finished. Convenience is useful, but the app contains information I would not want casually exposed. A few seconds spent checking device security and account recovery options is worthwhile.
Another setting-related habit is deciding how often I want to engage. Daily checking is not automatically better. For many people, a weekly or monthly review is enough unless they are actively investigating a problem or preparing for a major financial event. A fixed schedule makes the app useful without allowing it to become a source of unnecessary anxiety.
I would also make sure the app is kept current. The version I reviewed is 4.2.28 and requires Android 8.0 or later. That makes it accessible on many older Android phones, although anyone using an older device should still consider general security and performance, not only whether the app technically installs. On iOS or Android, keeping the operating system and the app maintained is part of using a finance service responsibly.
Shortcuts that make the routine faster
The fastest pattern I found is to give every visit a question. “Has anything changed?” is enough for a normal check. Before a planned application, the question becomes “Does my information look ready for closer review?” If I see something unfamiliar, I stop the routine and investigate instead of continuing through the app mechanically.
I also connect the check with existing habits. A monthly bill review, payday, or household finance session provides a natural reminder. This is better than relying entirely on memory, especially because credit monitoring is easy to postpone when nothing appears urgent. The app becomes more useful when it is attached to a habit that already exists.
For couples or families, I would avoid assuming that one person’s view represents everyone’s financial position. Each person should understand their own information and decide how to handle access. Sharing a phone or discussing household money does not automatically mean sharing account credentials. That small distinction protects privacy and keeps responsibility clear.
Another practical shortcut is to record the reason for an important check outside the app. If I am reviewing information before a car purchase, a rental application, or a refinancing conversation, I note the date and purpose in my personal finance notes. That gives the check context later and helps me avoid repeating the same investigation without knowing what I already reviewed.
Experienced users can also use the app as an early-warning prompt rather than a complete investigation tool. If something looks unusual, I gather supporting documents and contact the relevant organization through an appropriate official channel. I do not assume that tapping around in the app alone will resolve a disputed item. This is one of the most important trade-offs: the app can improve awareness, but the correction process may still require patience and communication elsewhere.
Where the app fits beside ordinary alternatives
The usual alternative is to rely on a bank app, a spreadsheet, or occasional paperwork. Those tools are still valuable, but they answer different questions. A bank app is excellent for transactions and balances, while a spreadsheet can show whether spending fits a plan. Experian® is more focused on the credit side of financial awareness, so it fills a gap rather than replacing either option.
Compared with a general budgeting app, this service feels narrower and more focused. That is a strength if the main goal is credit monitoring, but a weakness if someone expects detailed category budgets, shared household planning, investment tracking, or a complete net-worth dashboard. I would choose a budgeting tool for spending control and use Experian® alongside it when credit visibility matters.
Compared with checking credit only when a lender asks for information, the mobile approach is more proactive. It gives me a chance to notice questions earlier. The trade-off is that I must interpret what I see sensibly and avoid confusing monitoring with guaranteed approval for a future product. No credit app can remove the judgment involved in lending decisions.
The app’s free price makes it easy to try without committing money, which is useful for someone who wants a basic starting point. Still, “free” does not mean it replaces every financial service. I would judge it by whether it improves my awareness and habits, not by expecting it to become a complete financial command center.
Limits I would keep in mind
The first limitation is emotional. Credit monitoring can encourage reassurance-seeking, especially for users who check whenever they feel uncertain. If the app makes someone obsess over every change, a scheduled review may be healthier than constant attention. The tool is most helpful when it supports decisions, not when it becomes a source of daily stress.
The second limitation is that displayed information still needs interpretation. A user who sees an unexpected entry may not immediately know whether it is a mistake, a timing issue, or something connected with an account they forgot about. The app can point toward a problem, but the user must be willing to verify details and follow through.
The third is scope. This is a finance app, not a replacement for professional advice, a lender’s formal assessment, or a complete record-keeping system. Someone managing complex borrowing, business finances, or a disputed financial matter may need more specialized support. I would use the app as one convenient view, while keeping important documents and decisions organized elsewhere.
There is also a practical device question. The Android requirement of 8.0 or later is reasonable for a modern app, but people using very old phones may face broader security concerns even if installation is possible. I would not keep sensitive financial access on a device that no longer receives dependable system protection simply because the app opens successfully.
The age rating is Everyone, which reflects its broad accessibility, but that should not be confused with financial simplicity. Younger or inexperienced users may still need help understanding credit, borrowing costs, and the consequences of applications. The interface can make checking easier; it cannot replace financial education.
Who should use it, and who should choose something else?
I recommend Experian® to people who want a straightforward way to build credit awareness into a regular routine. It is especially suitable for someone preparing for a major purchase, recovering from a period of financial uncertainty, or simply trying to become more organized. It is also a sensible companion to a bank app because it covers a different part of the picture.
I would be more cautious about recommending it as the only finance app. If the main problem is overspending, a budgeting service may be more useful. If the priority is investment analysis, another specialist tool is a better fit. If someone needs detailed debt planning, they may benefit more from structured advice and a dedicated repayment workflow than from monitoring alone.
I would also tell a highly anxious user to establish boundaries before installing it. Decide how often to check, what counts as a reason to investigate, and where to keep notes. Without those boundaries, even a helpful monitoring tool can encourage unproductive checking.
My final assessment after building a repeatable habit
Experian® succeeds because it makes credit awareness easier to fit into ordinary life. I do not need to wait for a major application to think about whether my information looks familiar. A short, purposeful review can become part of a wider routine that includes bills, account security, and personal planning.
Its strongest use is not dramatic. It is the quiet advantage of noticing questions earlier, separating a genuine issue from a momentary worry, and arriving at important financial conversations better prepared. The app’s 4.7 average and broad adoption match my overall impression: it is a well-established, accessible option for people who want a dedicated credit-monitoring habit.
My recommendation comes with a clear condition: use it as a monitoring layer, not as your entire financial system. Keep your own records, verify anything important, protect access, and choose a sensible checking schedule. With that approach, the free app from Experian is a practical addition for everyday credit awareness. Without it, users may expect a complete budget, instant solutions, or a guaranteed outcome that the app cannot provide.
For me, the deciding question is simple: do I want a convenient way to stay informed about credit between major financial events? If the answer is yes, this app is worth trying. If I need detailed spending control or specialized financial planning, I would pair it with a more focused alternative rather than asking it to do a job it was not designed to handle.
Experian® FAQ
What is Experian®, and what can I use it for?
Experian® is a credit and identity-monitoring service that helps users review information connected to their credit profile. Depending on your location and selected plan, the app may provide access to a credit score, credit report details, monitoring alerts, personalized recommendations, identity-protection tools, and educational resources. Available features can vary by country, eligibility, and subscription level.
Is Experian® free to download and use?
The Experian® app can generally be downloaded at no cost, but not every feature is free. Users may receive access to selected credit information and basic monitoring without paying, while advanced identity protection, broader monitoring, or additional reports may require a subscription. Before starting a trial or paid plan, carefully review the price, renewal terms, and cancellation policy shown in the app.
Does using Experian® affect my credit score?
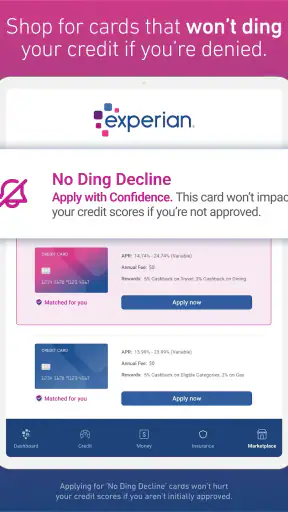
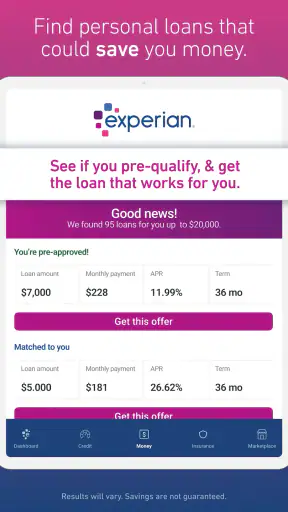
Checking information through Experian® typically uses a soft inquiry, which does not lower your credit score. However, the app may also connect you with lenders, credit cards, loans, or other financial products. If you apply for one of those products, the provider could perform a hard inquiry that may affect your score. Always read the application disclosures before submitting an offer request.
What personal information does Experian® require?
Because Experian® provides credit and identity-related services, it may request personal details such as your name, address, date of birth, and identification information to verify your identity and match your records. You may also need to create login credentials and provide security answers. Review the privacy policy and app permissions so you understand how your information is collected, used, stored, and shared.
Is Experian® safe to use, and what should I do if I find an error?
Experian® uses account-security and identity-verification measures designed to protect sensitive information, but no online service can eliminate every security risk. Use a strong, unique password and enable available security options. If your report contains inaccurate or unfamiliar information, use the dispute or support tools provided by Experian®, and contact the relevant creditor if additional verification is required.











